Beyond The Housing Fair:
Making Homeownership Add Up
NOVEMBER 3, 2026 | TUESDAY


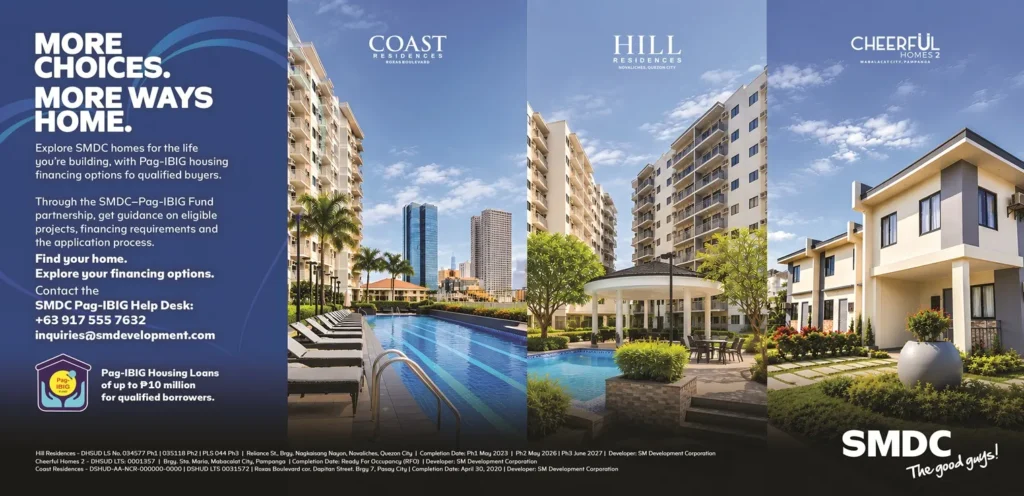
National Shelter Month, held every October, highlights the importance of adequate housing and sustainable communities in improving the lives of Filipino families. For prospective homeowners, the observance also offers an opportunity to consider what it takes to turn the aspiration of owning a home into a realistic financial commitment.
Housing fairs, which often take place throughout the month, make the search for a home more accessible by bringing developers, residential displays, and financing information into one venue. But once a prospective buyer finds a promising property, a more important question follows: Can the household realistically afford it, not just today, but for the years to come?
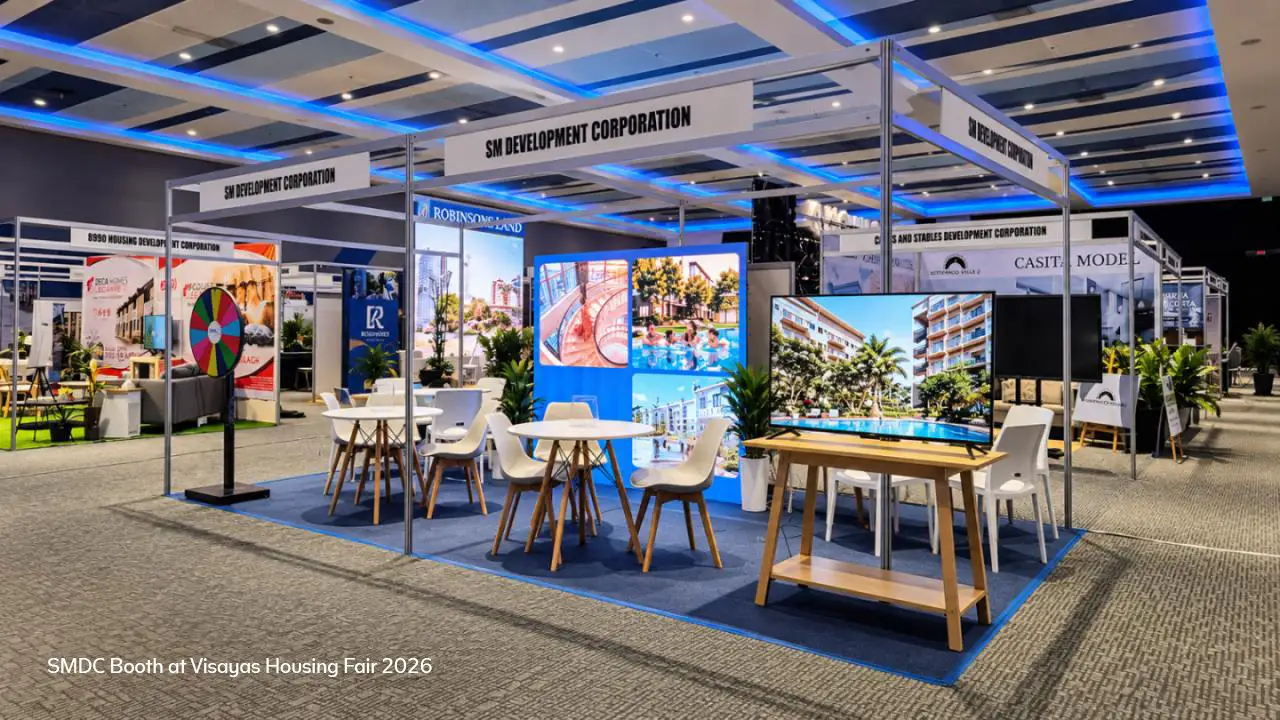
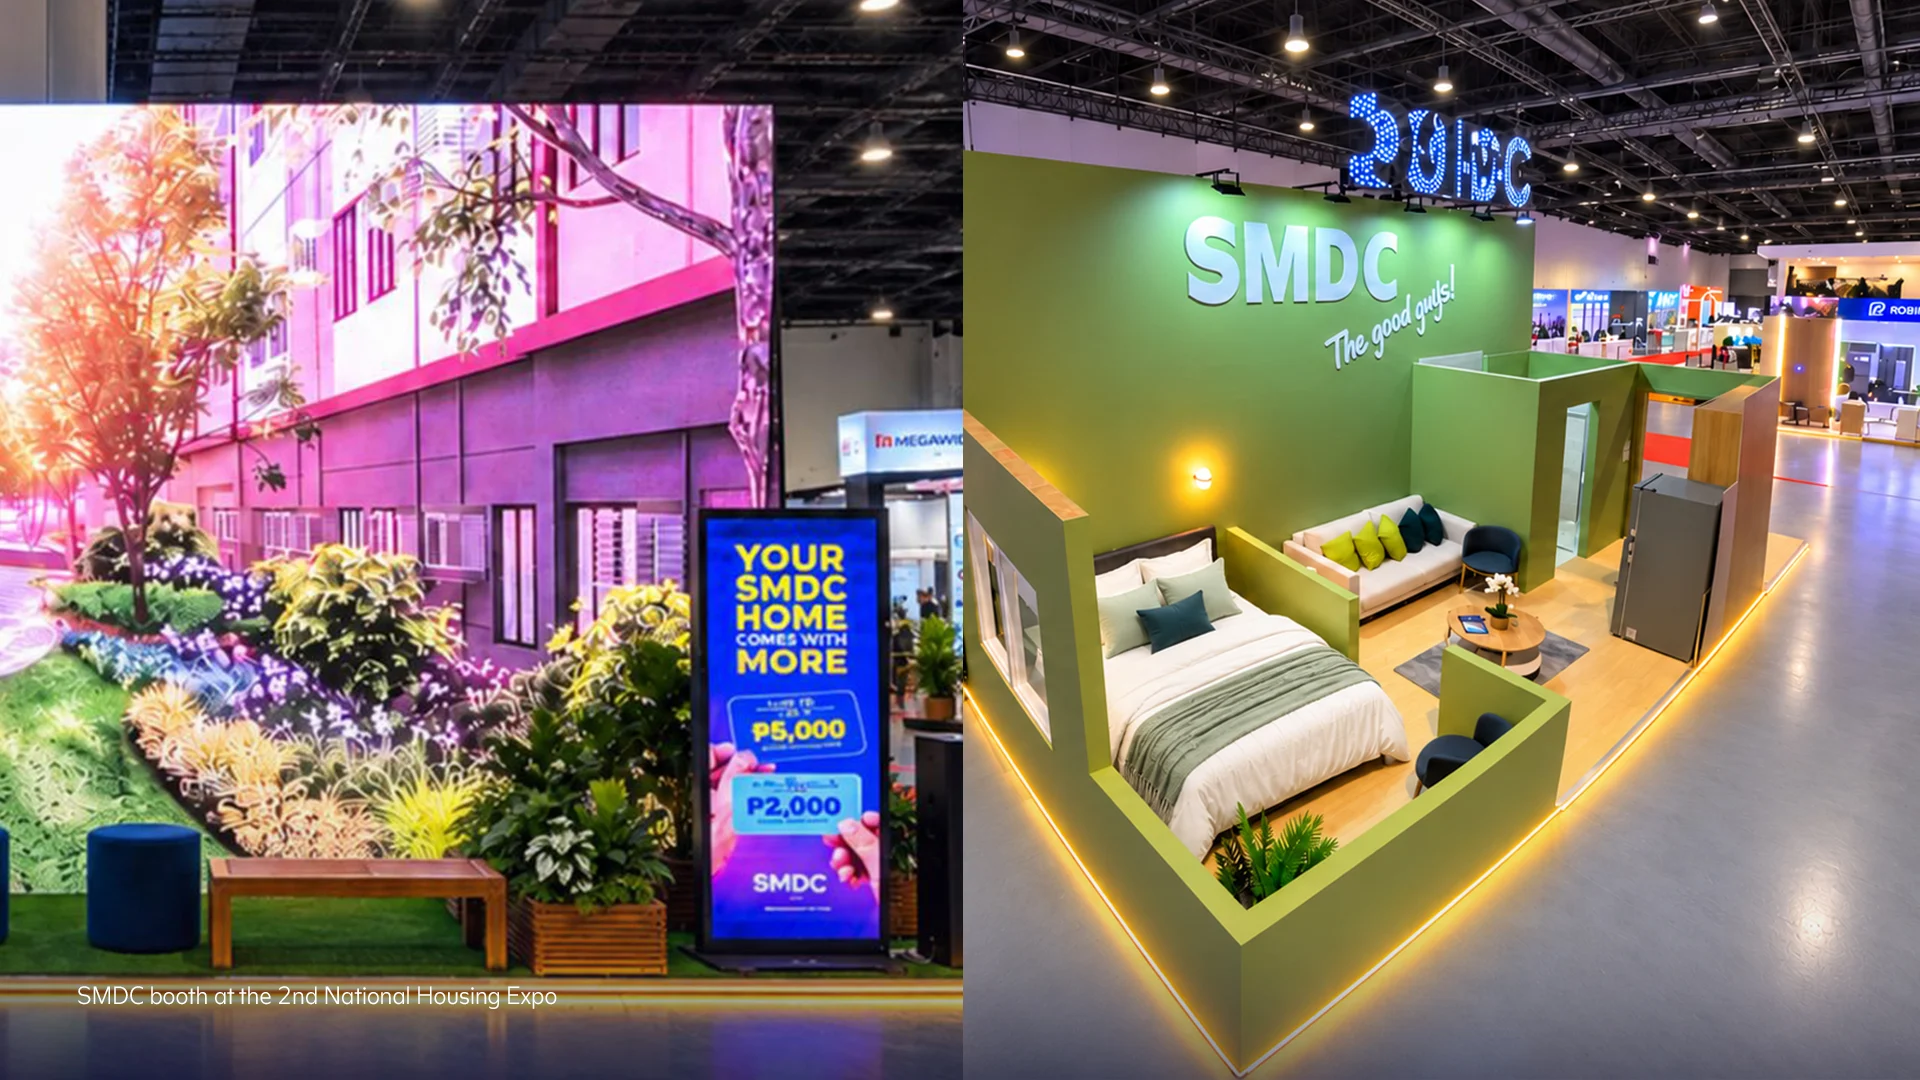
At the National Housing Expo, SMDC presented its residential offerings through immersive community displays and a walk-through mock-up unit, allowing visitors to explore potential living spaces. At the Visayas Housing Fair extended these opportunities to regional homebuyers through Smile Residences in Bacolod, Parkville residential lots in the city, and Glade Residences in Iloilo.
Read more topic related to Ilolo and Bacolod Properties
Glade Residences Progress Marks Next Chapter in Iloilo’s Growing Communities
Parkville Moves From Vision to Ground: A Master-Planned Community Takes Shape in Bacolod
These events illustrate how housing fairs can serve as starting points for informed property decisions. Beyond viewing developments, prospective buyers can ask questions, compare options, and seek guidance on financing.
Through its participation in housing fairs, SMDC gives prospective buyers opportunities to explore residential options and ask property-specific questions. Moreover, its partnership with Pag-IBIG Fund connects this property information with buyer education, estimated financing computations, and application preparation, helping households understand their options and prepare their next steps toward homeownership.
Asking the right questions
For households considering their next home to move into, the next step after discovering a promising property is to understand the full terms of the purchase. Buyers should request the complete selling price, payment schedule, expected contractual turnover date, and available financing arrangements.
They should also clarify reservation conditions, applicable taxes and transaction charges, and other expenses excluded from the quoted price. Comparing written quotations and payment schedules can help households assess their options based on actual financial commitments rather than initial impressions.
These considerations apply whether a buyer is exploring a condominium in Metro Manila or a residential lot in Visayas. While properties differ in price, location, and intended use, each requires a clear understanding of the costs and obligations involved.
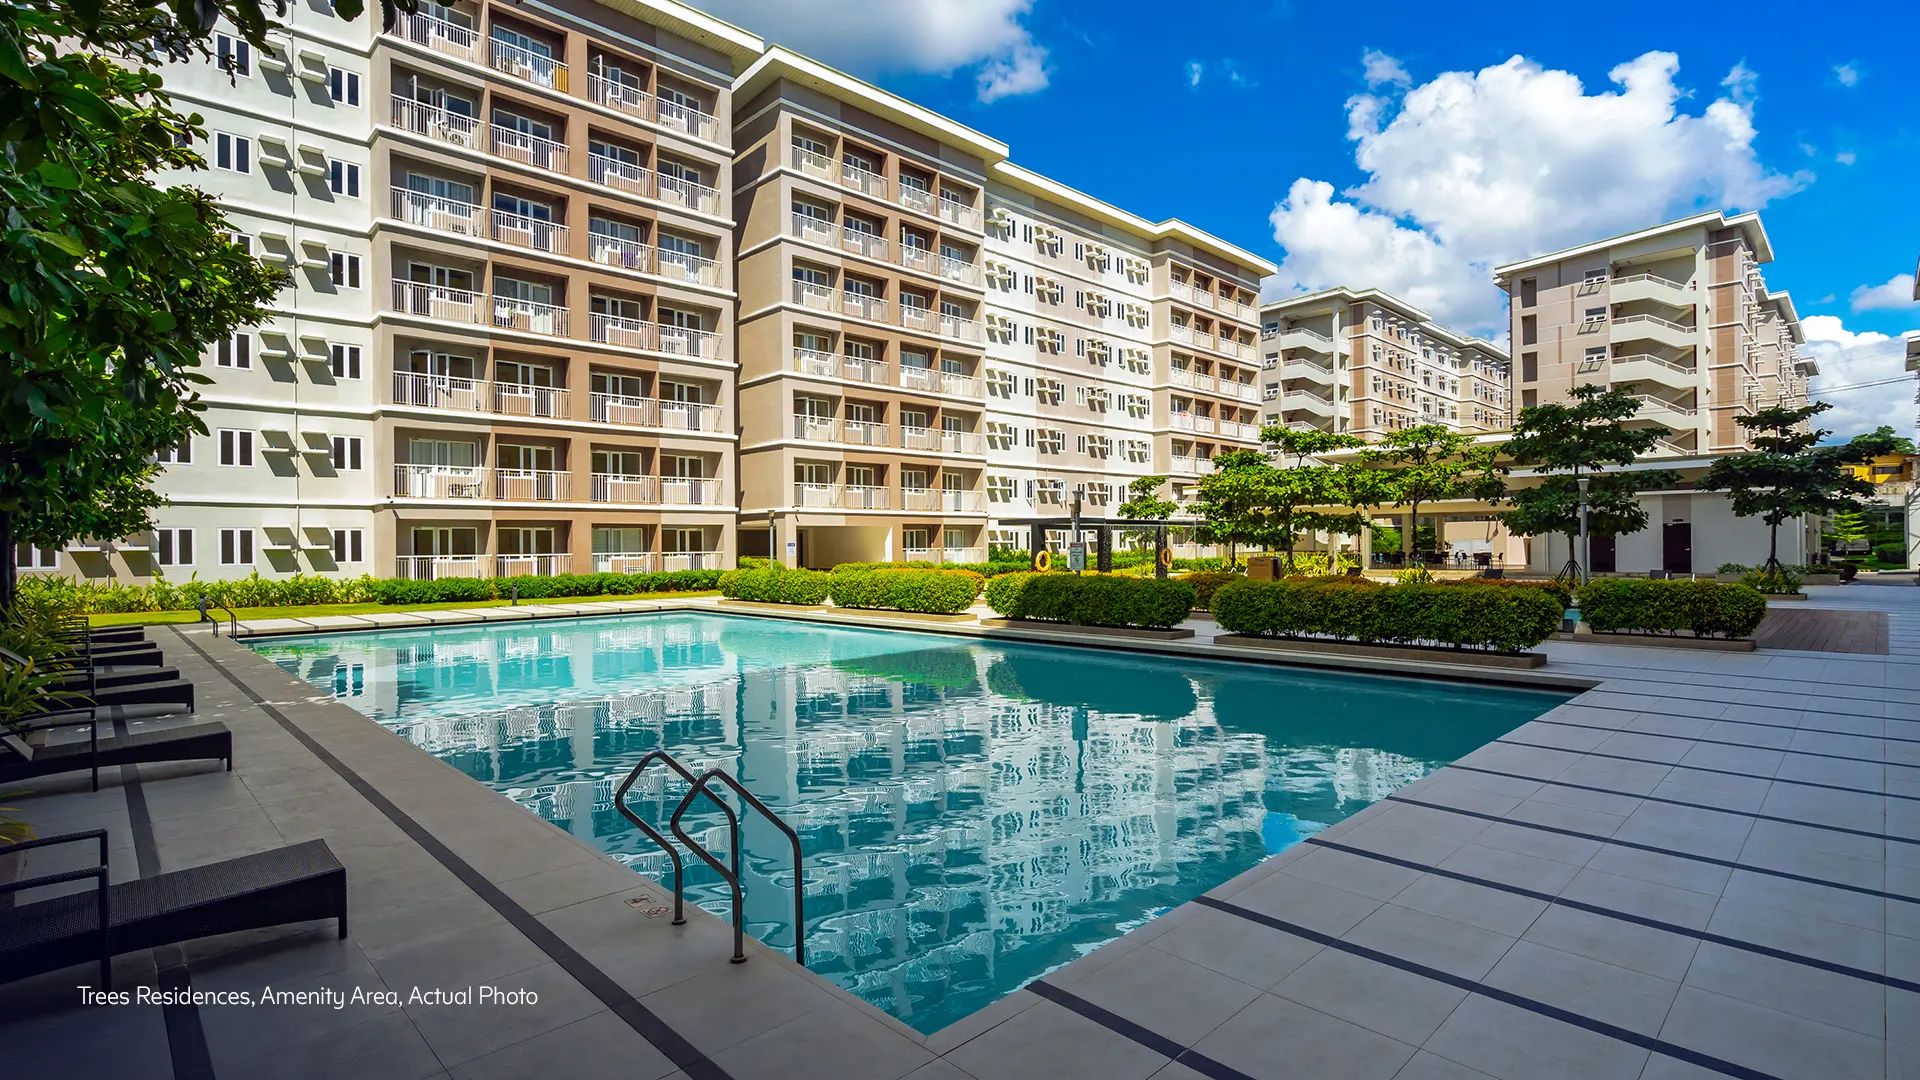
Understanding the payment journey
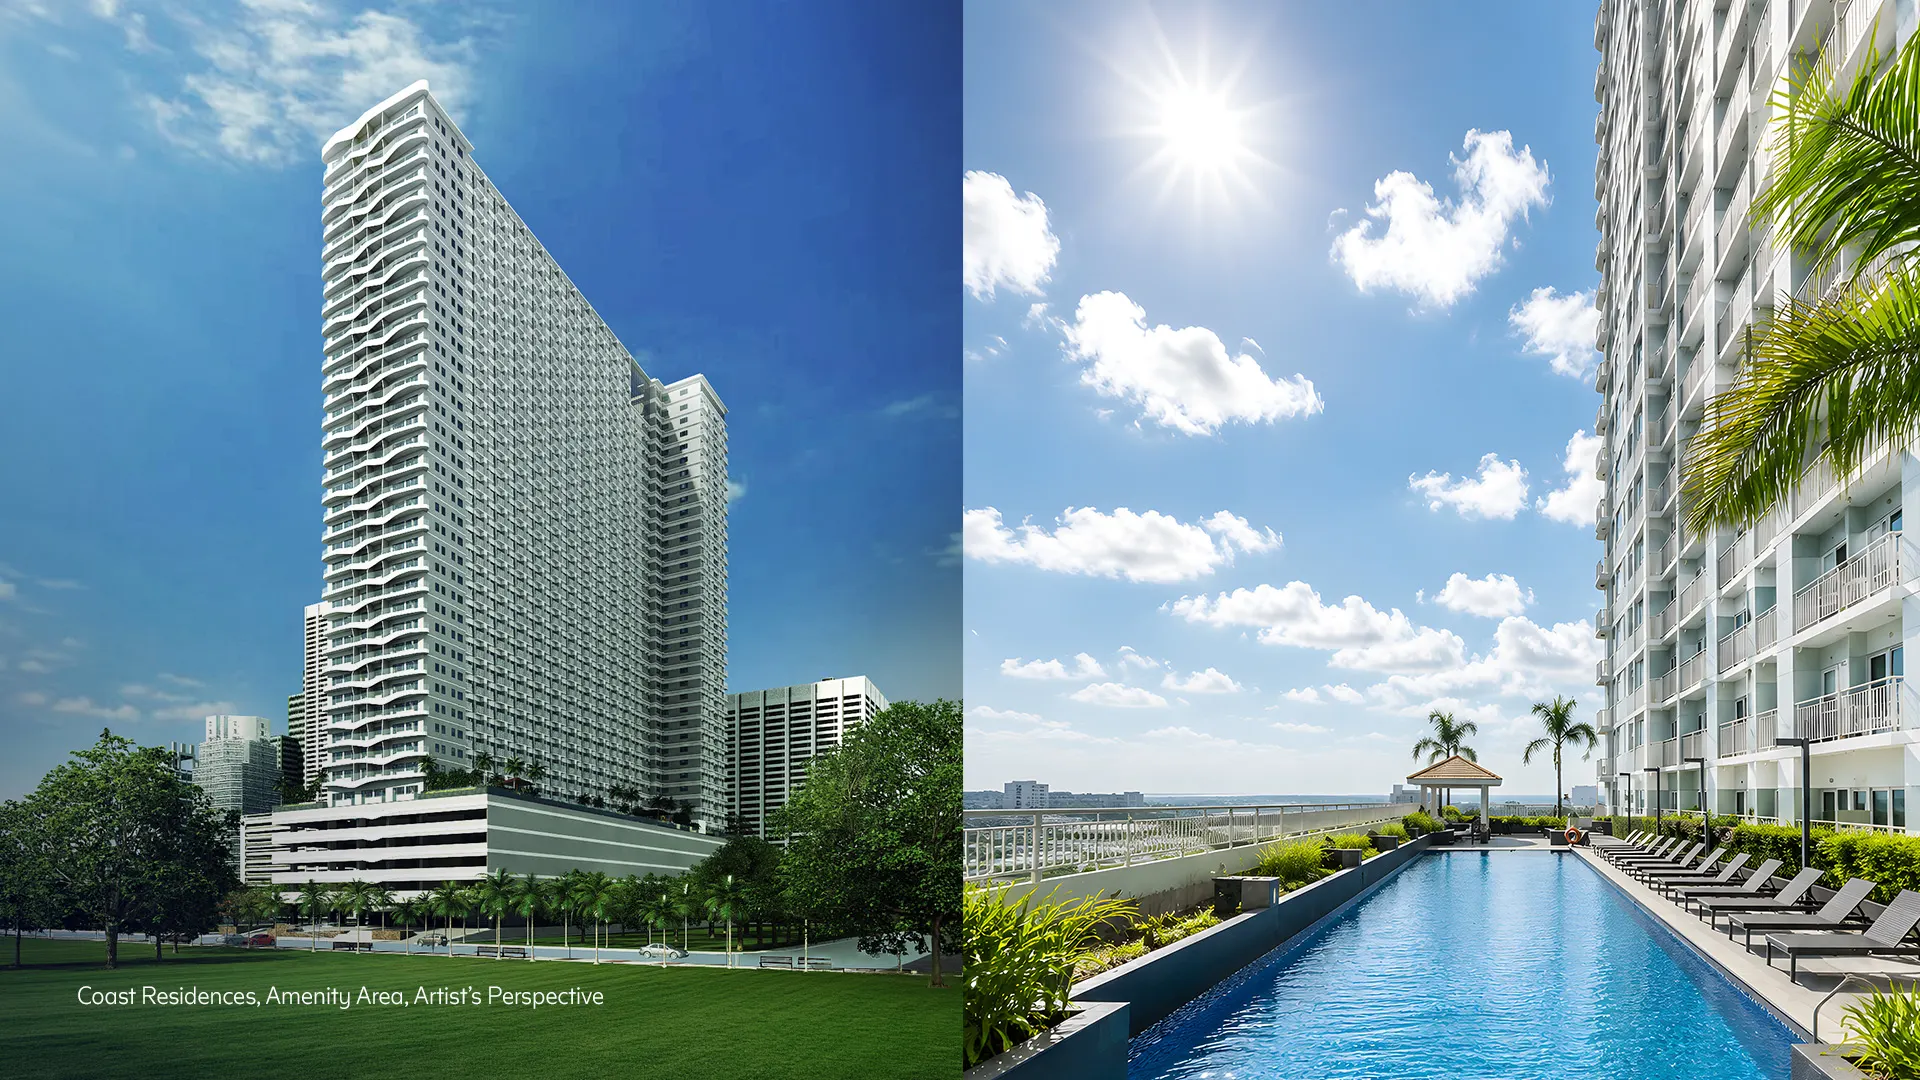
Once a home is selected, purchasing a home still involves several stages, from reservation and equity or down payments to loan application, approval, and eventual release of financing. Buyers should understand when payments fall due, which requirements must be met at each stage, and how the payment schedule relates to the financing process.
A sample computation can provide an initial estimate, but it should not be mistaken for a formal financing commitment. Actual loan amount, repayment terms and approval depend on the lender’s assessment and applicable requirements. Pag-IBIG Fund’s published application checklist, for example, identifies proof of income and valid identification among the requirements for certain housing-loan applications.
Seeking guidance early allows buyers to prepare the necessary documents, clarify project eligibility, and understand the contractual arrangements that apply if financing terms change or an application does not proceed as expected.
Budgeting beyond monthly amortization
Monthly loan payments are only one part of the cost of homeownership. Buyers must also consider applicable taxes and transfer expenses, insurance, association dues, utilities, maintenance, and move-in costs. The amounts will depend on the property and financing arrangement, making it important to obtain project-specific information before committing.
Location also affects the household budget. A property with a lower purchase price may involve longer commutes or higher transportation expenses. A home closer to workplaces, schools, healthcare facilities, and essential services may help reduce recurring costs and travel time.
These considerations matter when evaluating developments in both urban and regional settings. The objective is not simply to find the lowest-priced property, but to identify a home whose total cost and location suit the household’s needs over time.
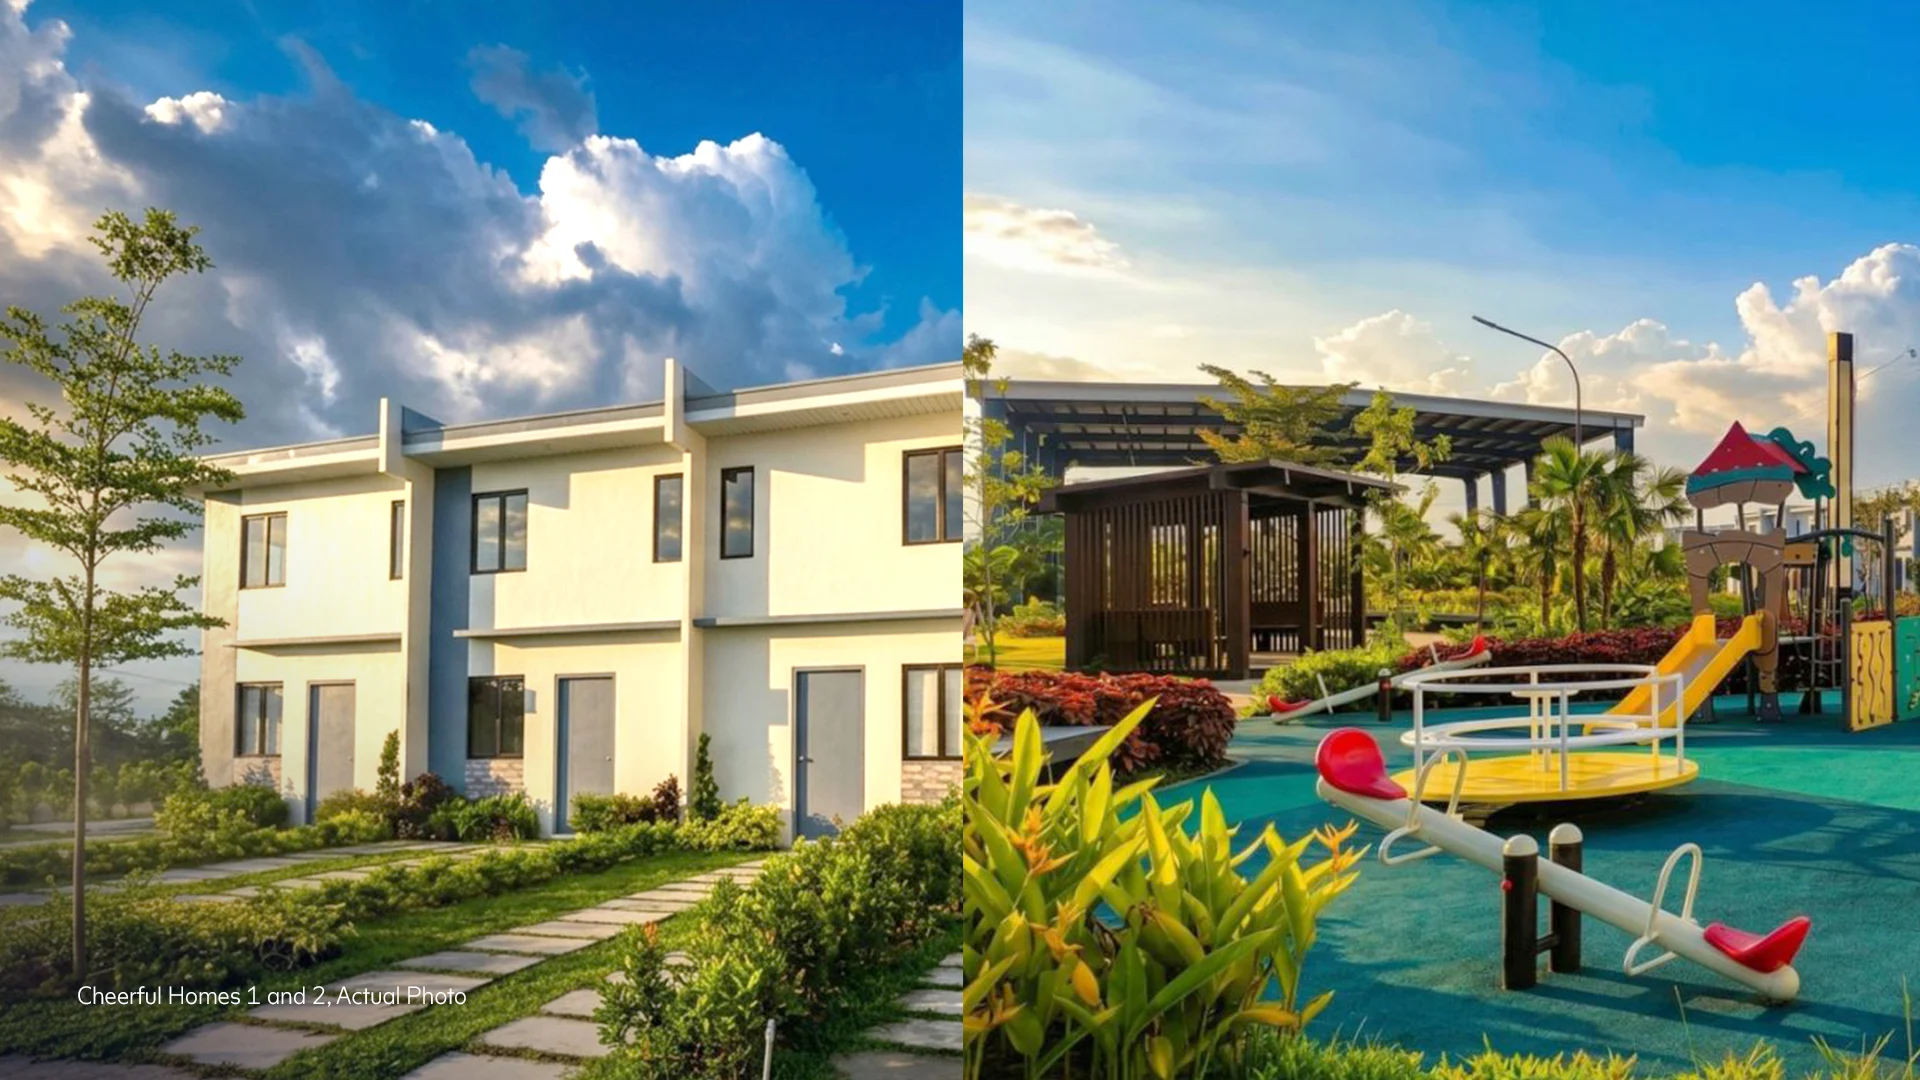
Responsibly preparing for financing
Before applying for a housing loan, households should assess their net disposable income, existing liabilities, and regular living expenses. The amount remaining after essential obligations offers a more realistic basis for determining what monthly payment they can sustain.
An emergency fund should also remain part of the financial plan. Unexpected medical expenses, home repairs, or income disruptions can place pressure on a household already committed to regular loan payments. A sustainable plan accounts for these possibilities rather than assuming that income and expenses will remain unchanged.
Housing fairs and financing consultations can help prospective homeowners identify the information they need to move forward. By combining property inquiries with a realistic assessment of their finances, buyers can better determine which options align with their circumstances and long-term goals.
Making informed plans
National Shelter Month underscores the importance of housing as a foundation for household stability and sustainable communities. Turning that aspiration into ownership, however, requires more than finding a suitable property. It calls for clear information, careful financial planning, and an understanding of the responsibilities that come with a home.
Through housing fairs and its partnership with Pag-IBIG Fund, SMDC contributes to an environment where prospective buyers can explore residential options and seek guidance on their next steps.
Ultimately, the value of these opportunities lies in helping households make informed decisions based on their housing needs and financial capacity. A well-prepared homeownership plan begins with asking the right questions and understanding the commitment before taking the next step.
Read more:
SMDC x PAG-IBIG Financing FAQs
A Home of Your Own Starts with Knowing Your Options